Your Rent Is Building Equity. Just Not Yours.
Renting another 5 years could cost you $150,000*
One free hour, just for RedT Homes residents. Jeff Aronheim will show you:
- What waiting is really costing you. We’ll work it out in real dollars, not guesses.
- How to get into your home sooner with a special RedT Homes incentive.
- How to stop paying someone else’s mortgage and start building wealth of your own.
You’ll leave knowing exactly where you stand and what your next step is. Bring your questions.
Reserve your free seat
Wed, Nov 18 · 6:00 PM – 7:00 PM MT · Zoom link emailed instantly
✓ Name and email only. No credit check, no application, no obligation.
A free one-hour Zoom class for RedT Homes residents. See how you could buy with $0 down using CrossCountry Mortgage’s CCM ZeroDown program, and how a 6% builder concession from RedT Homes can be used to buy down your interest rate. Jeff will cover the specifics live.
*See example and program disclosures below. Not all borrowers will qualify. Why attend ↓
The two things that keep renters renting, handled.
You already make a housing payment every month. For most renters, two hurdles stand between that rent check and owning: saving a down payment and a monthly payment that feels out of reach. This plan goes after both.
Down payment with CCM ZeroDown
CrossCountry Mortgage’s CCM ZeroDown program is built to help eligible buyers purchase with $0 down. No years of saving before you can stop renting.
Builder concession from RedT Homes
RedT Homes is offering a concession of 6% of the purchase price ($41,940 on a $699,000 purchase price) that can be used to buy down your interest rate and lower your monthly payment.
Your numbers, explained live
In one hour, Jeff will show how the two work together, who qualifies, and how to get a personalized rent vs. own analysis for your situation.
*Equity example: about $150,000 ($149,502) in estimated equity after 5 years of owning, calculated as estimated home value minus the remaining loan balance. Based on a $699,000 purchase price with $0 down using CCM ZeroDown, where the FHA first mortgage and the down payment assistance second mortgage together total $709,485 (101.5% of the price), so estimated equity starts at -$10,485. After 5 years, the home value is estimated at $810,333, assuming 3% annual home-value appreciation, and the combined loan balance is estimated at $660,831 after estimated principal paydown of $48,654. Equity shown is before any costs of selling. Illustration only; not a guarantee of future home values, which can go down as well as up. Your results will vary.
Example and program disclosures. Example based on a $699,000 purchase price with a 6% seller concession ($41,940) from RedT Homes, applied toward a rate buydown, and $0 down payment using CrossCountry Mortgage’s CCM ZeroDown program. CCM ZeroDown pairs an FHA-insured first mortgage with down payment assistance of 3.5% or 5% of the purchase price, provided as a repayable second mortgage (second lien) with its own interest rate and monthly payment. It is not a grant. Closing costs and FHA mortgage insurance still apply. At least one borrower must occupy the home as a primary residence. Down payment assistance amounts and interest rates are subject to program guidelines; higher assistance amounts may be associated with higher interest rates. Eligibility depends on the borrower’s full profile, including credit, income, assets, debt-to-income ratio, property type and occupancy, and other underwriting guidelines. Not all borrowers will qualify. Seller/builder concession amount, eligibility and availability are set by RedT Homes and may change; limits apply, including the maximum concession permitted by the loan program. This is not a commitment to lend. All loans are subject to credit approval and underwriting. Programs, rates, terms and conditions are subject to change without notice. Jeffrey Aronheim NMLS #235233; Branch NMLS #1773803; CrossCountry Mortgage, LLC NMLS #3029 (nmlsconsumeraccess.org). Equal Housing Opportunity.
In this class, you’ll learn
Rent vs. own, side by side
What your rent could look like as a mortgage payment, and how ownership builds equity for you.
How the 6% concession buys down your rate
How a rate buydown works, what it could mean for your monthly payment, and who’s eligible. Concession offered by RedT Homes; terms set by RedT.
“Can I qualify for $0 down?”
How CCM ZeroDown works, what lenders look at (credit, income, savings), and what you can do now to get ready.
Your 90-day game plan
What you can do now to be ready, even if buying is a year away.
This class is for you.
Jeff Aronheim
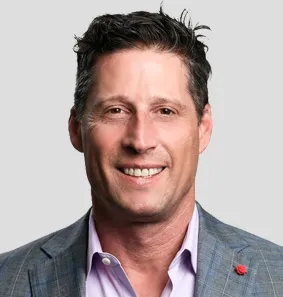 Jeff AronheimLoan Officer
NMLS #235233
Jeff leads Team Aronheim at CrossCountry Mortgage in Greenwood Village and has been serving families since 2005. He’ll walk you through the numbers in plain English and stay on to answer your questions.
“Jeff was fantastic to work with. He was by our side every step of the way as we purchased our home. We knew that he was looking out for our best interest throughout the whole process. We would highly recommend Team Aronheim!”
Jasie H. · February 11, 2026“With Jeff and his team the process was smooth with good communication from day 1. I appreciated the funds being at the title company in the morning of the day of closing.”
Martin · February 11, 2026Wednesday, November 18, 2026
| Date | Wednesday, November 18, 2026 |
| Time | 6:00 PM – 7:00 PM MT (Mountain Time) |
| Format | Live on Zoom. Your link is emailed right after you register, plus reminders. |
| Duration | 1 hour, including live Q&A |
| Cost | Free |
| Hosted by | Jeff Aronheim, Loan Originator, CrossCountry Mortgage (NMLS #235233) |
Reserve your free seat for Wed, Nov 18
6:00 PM – 7:00 PM MT · 1 hour · Live on Zoom
✓ Name and email only. No credit check, no application, no obligation.
Rather talk now? Book a free call → or call 720-200-5464
FAQ
Who is this class for?
RedT Homes residents who rent today and are curious about owning. You don’t need to be ready to buy yet.
When and where is it, and how long does it take?
Wednesday, November 18, 2026, 6:00 PM – 7:00 PM MT, live on Zoom. It runs about one hour, including Q&A. We email your Zoom link after you register.
What do I need to register?
Just your full name and email address.
Does registering commit me to anything?
No. Registering only holds your seat. It isn’t an application, there’s no credit check, and it doesn’t obligate you to buy.
Can I talk to someone before the class?
Yes. Schedule a one-on-one, or call 720-200-5464.
Which homes does the builder incentive apply to?
The builder incentive is offered and administered by RedT Homes. Eligible homes, communities, terms and availability are determined by RedT Homes and may change. Your loan eligibility is determined separately through underwriting.
Is $0 down really possible?
Yes, for eligible buyers. CCM ZeroDown from CrossCountry Mortgage pairs an FHA first mortgage with down payment assistance (3.5% or 5% of the price) provided as a repayable second mortgage, so the down payment can be financed. Closing costs and FHA mortgage insurance still apply, and not all borrowers will qualify. We’ll explain the details in class.
How does the 6% builder concession lower my rate?
RedT Homes is offering a concession of 6% of the purchase price that can be used to pay for a rate buydown, which lowers your interest rate and monthly payment. The concession amount, eligibility and terms are set by RedT Homes and may change.
How will my information be used?
We use your name and email to send your Zoom link and reminders, and Team Aronheim may follow up about your homeownership options. See the Privacy Statement.
$0 down. 6% builder concession.
One free hour to see if you could own instead of rent.
Jeffrey Aronheim with CrossCountry Mortgage | NMLS# 235233 | Branch NMLS# 1773803 | CrossCountry Mortgage, LLC NMLS# 3029 · NMLS Consumer Access · Disclosures & Licensing
 Equal Housing Opportunity
This article is for educational purposes and does not constitute a commitment to lend, an offer of credit, or legal or financial advice. Rates, program guidelines and loan limits are current as of October 28, 2026. All loan scenarios are illustrative composites; individual results depend on credit, income, property and program eligibility. Lender overlays vary. Equal Housing Opportunity.